Research

Taxation, innovation, and disclosure.

Job Market Paper

From Secrecy to Patenting: The Disclosure Effects of Patent Box Incentives

Sole-authored

Patent box regimes raise firm patenting by inducing a substitution away from trade secrecy, with downstream effects on peer productivity and industry structure.

Abstract

Patent boxes have emerged as a prominent innovation tax incentive. They offer preferential tax rates on qualifying intellectual property income commonly tied to patent protection. I examine whether these regimes induce firms to substitute from trade secrecy toward patenting. Using their staggered adoption across Europe, I document a large and immediate increase in patenting, consistent with firms bringing unpatented inventions into the public patent system. The response varies with prior protection practices, proprietary disclosure costs, and regime design in ways predicted by the substitution mechanism, while real innovation inputs show little contemporaneous response. Confidential survey evidence around Portugal's 2014 adoption provides direct support for the substitution mechanism: secrecy use declines as patent use rises. Consistent with downstream knowledge-diffusion effects, post-adoption productivity gains increase with firms' technological exposure to the expanded patent stock, while industry concentration declines. These findings highlight a disclosure channel through which patent boxes promote knowledge diffusion, a margin that traditional R&D tax credits do not directly target.

Presentations

13th Annual Mannheim Taxation Conference, 2026 AAA/Deloitte Foundation/J. Michael Cook Doctoral Consortium, HKAAA Rookie Camp 2026, University of Hong Kong
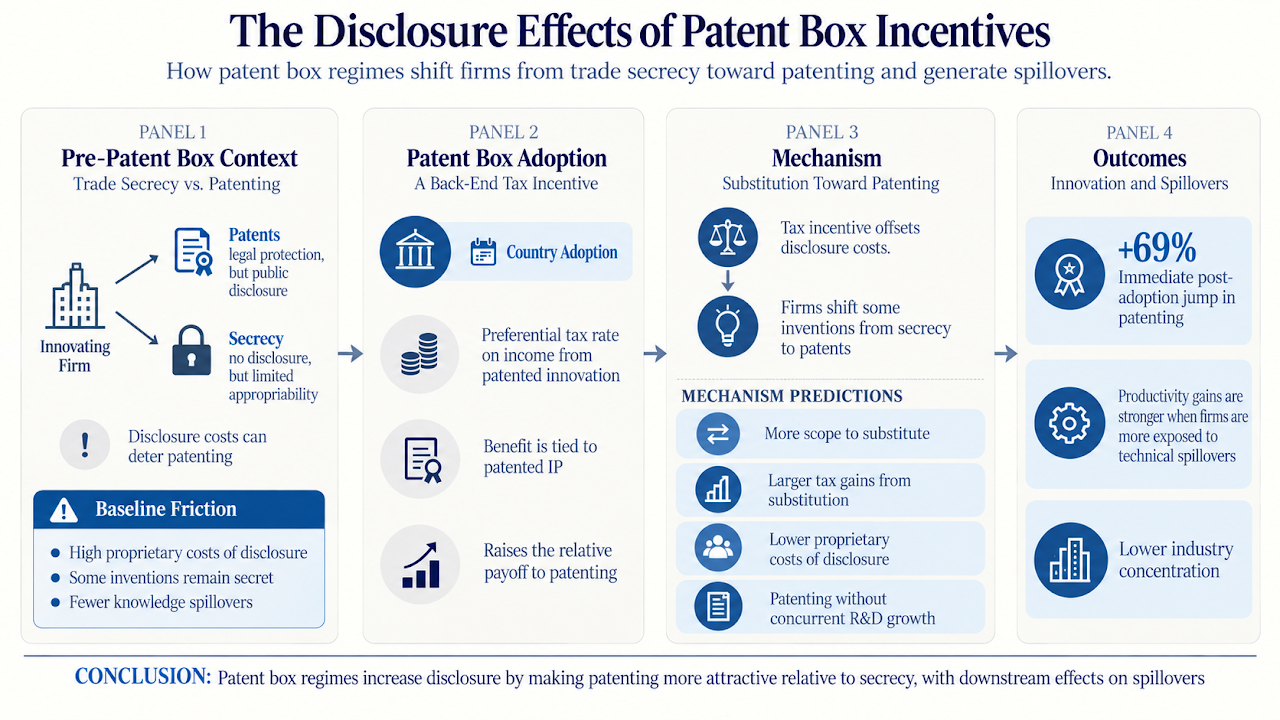
Patent box incentives make patenting more attractive than trade secrecy, with downstream effects on knowledge spillovers and industry concentration.
Paper overview · open full size

Working Papers

Does Tax Complexity Hinder Innovation?

with John Gallemore and Ed Maydew

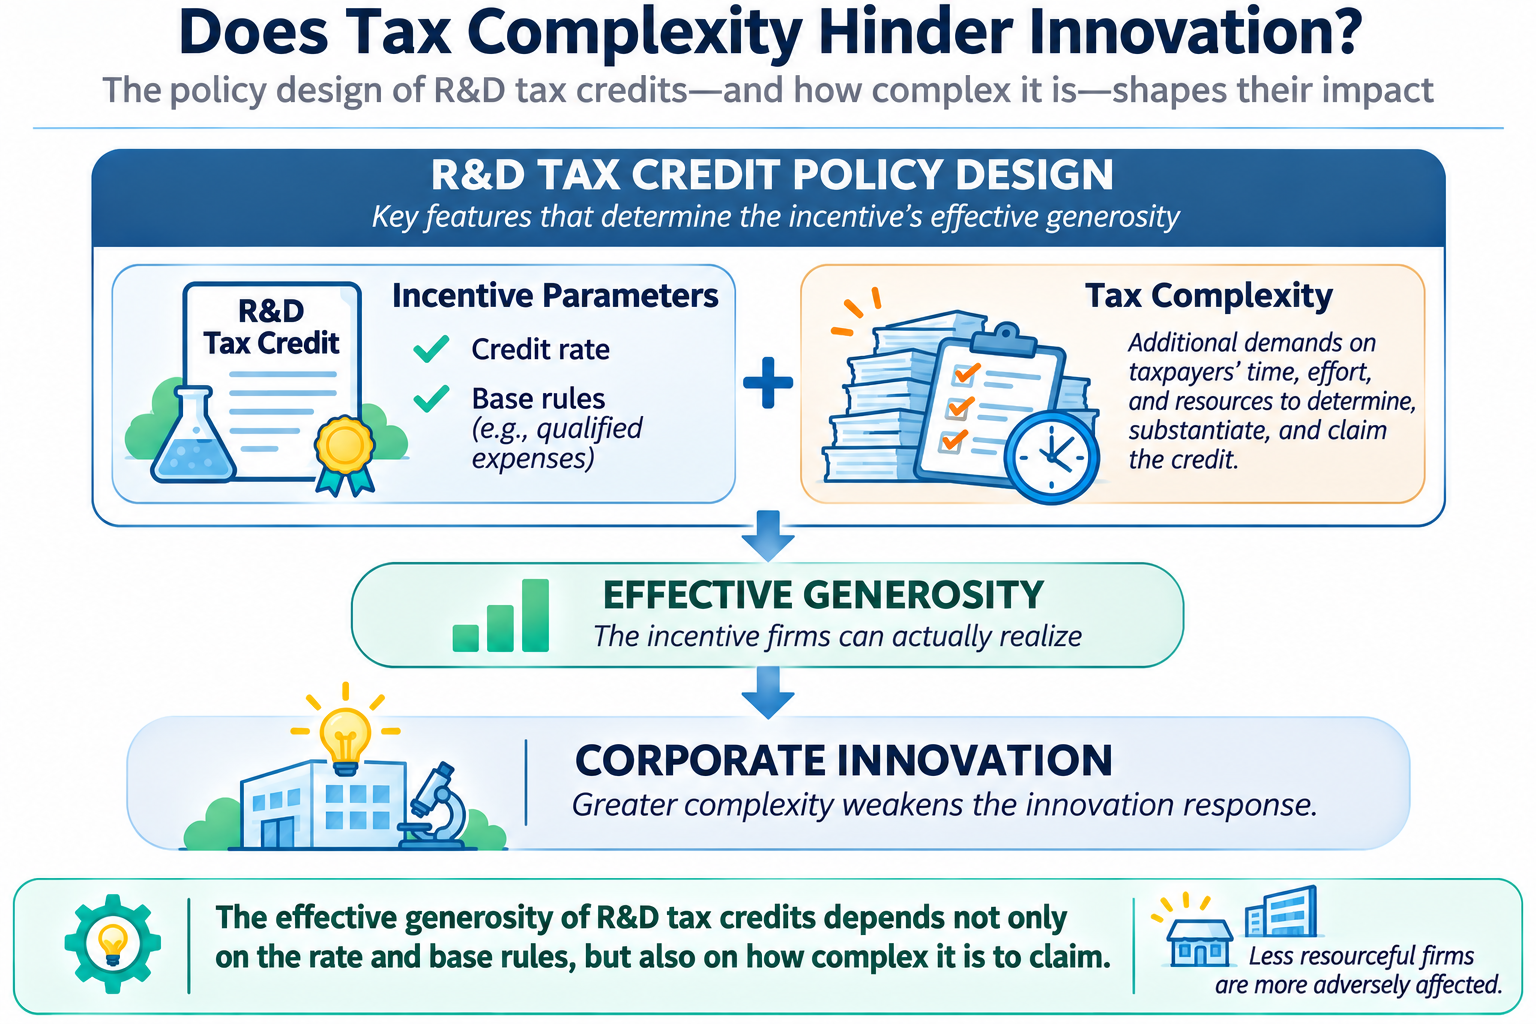
Tax complexity shapes the efficacy of R&D tax incentives in spurring innovation. Across U.S. state R&D tax credits, tax complexity that increases administrative frictions and compliance burdens meaningfully attenuates the credit’s intended innovation impact.

Abstract

We examine whether tax complexity hinders the effectiveness of tax incentives that are intended to promote innovation. While many jurisdictions offer tax incentives for innovative activities, these incentives vary widely in their complexity, which may affect the extent to which they stimulate innovation. Exploiting variation across U.S. states over four decades, we develop a novel, time-varying measure of complexity in state-level R&D tax credit policies. We find that while larger R&D tax credits are positively associated with future corporate patenting, the effect is attenuated when tax credit complexity is high. This attenuation varies cross-sectionally based on the type of tax complexity and with firm characteristics. Finally, we find that while R&D tax credits are associated with lower innovation novelty on average, tax complexity does not materially moderate this effect. Overall, our findings indicate that tax complexity hinders the effectiveness of innovation incentives, with important implications for policy design and knowledge spillovers.

Presentations

16th European Conference on Current Research in Taxation, Penn State*, HKU

* Presented by a coauthor

Tax complexity weakens the effect of state R&D tax credits on corporate patenting.
Paper overview · open full size

Disclosing to Politicians

with John Gallemore, Jeff Hoopes and Irene Tan

Revise and resubmit at Journal of Accounting Research

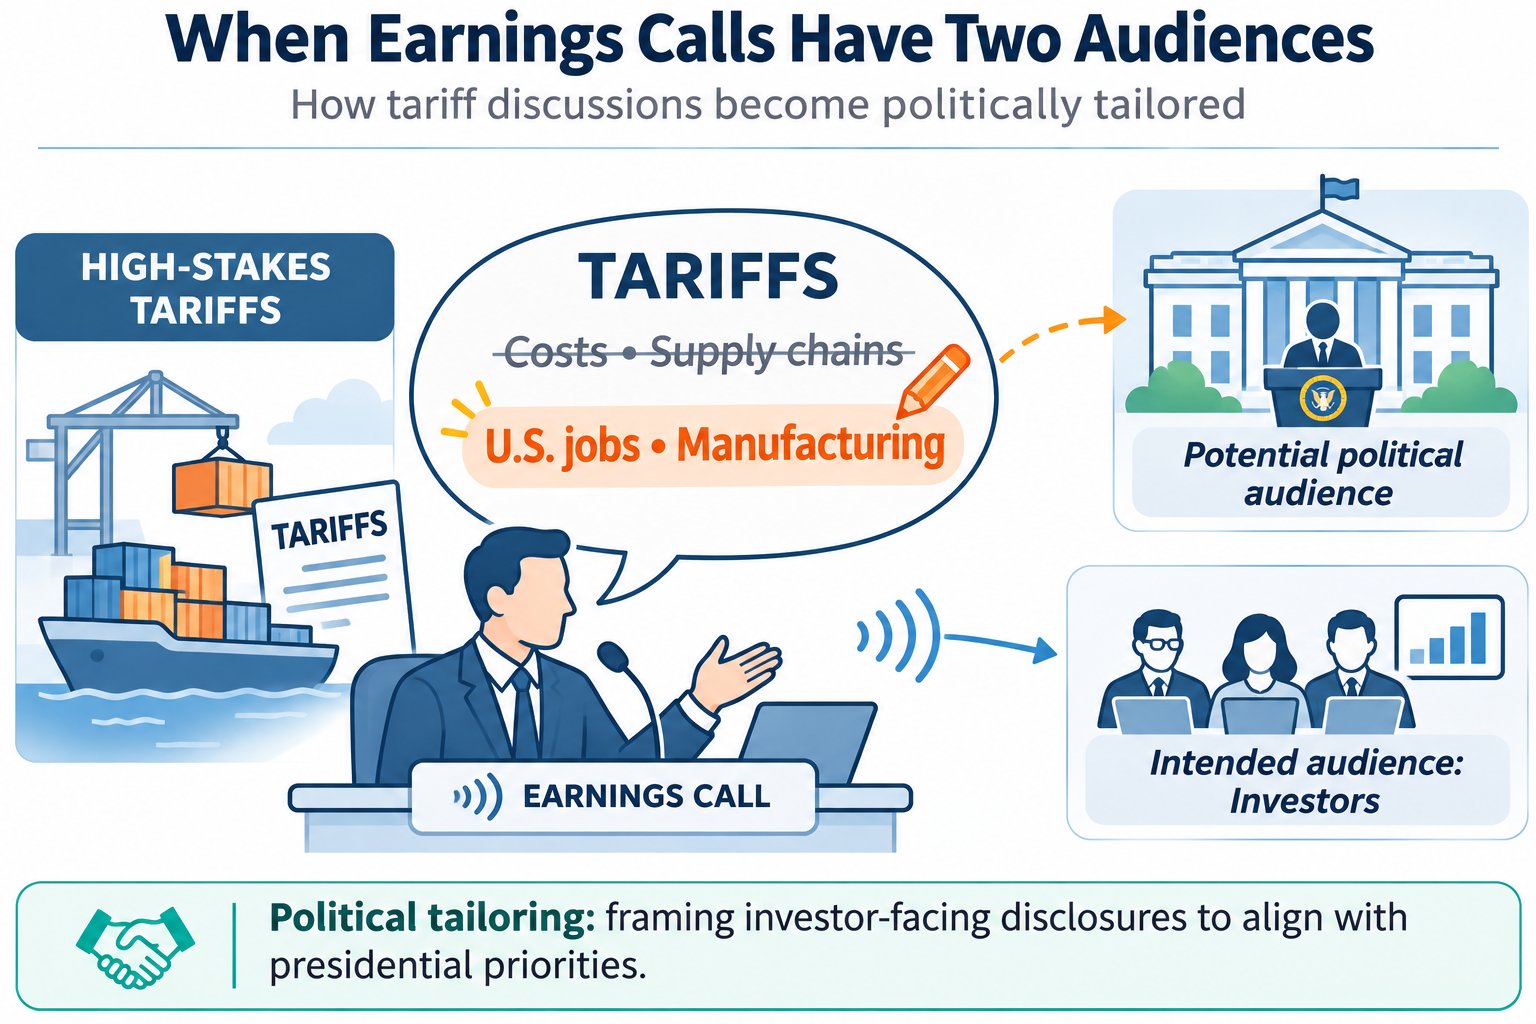
Firms strategically tailor their disclosures about tariff policies to align with the policy stance of strong politicians, and this political tailoring yields tangible regulatory benefits at the cost of reduced quality of disclosure to investors.

Abstract

We examine whether public companies change their disclosures to align with the policy preferences of powerful political actors—which we refer to as “political tailoring.” Focusing on the setting of President Donald Trump’s first and second terms in office, we study the political tailoring of discussions around tariffs, an issue with both substantial policy salience and cash flow implications. Using earnings conference call transcripts, we employ a large language model to classify the extent to which tariff discussions are politically tailored. We find that firms with incentives to appease those in charge of tariff policy, such as firms who are the most exposed to tariffs, firms that engage in other forms of political catering, such as via PAC contributions and lobbying, and firms with Republican CEOs engage in greater political tailoring of these disclosures. We find evidence consistent with this tailoring having payoffs: political tailoring is positively associated with the granting of tariff exemptions during the first Trump administration, but not with the awarding of government contracts. We also find that political tailoring is negatively (positively) associated with disclosure readability (verbosity), suggesting that a potential cost to political tailoring is less informative disclosures. Our findings contribute to literatures on political influence and corporate disclosure by documenting a novel form of non-financial strategic communication with potential implications for transparency and firm value.

Presentations

32nd JATA Conference, 2025 Kellogg Accounting Conference*, Kelley Accounting Research Symposium*, UNC Chapel Hill, North Carolina State*, UConn*, UIowa*

* Presented by a coauthor

Firms tailor tariff disclosures to powerful politicians, gaining tariff exemptions while reducing disclosure readability.
Paper overview · open full size

Government Certification and Global Trade

with Guoman She and Le Zhao

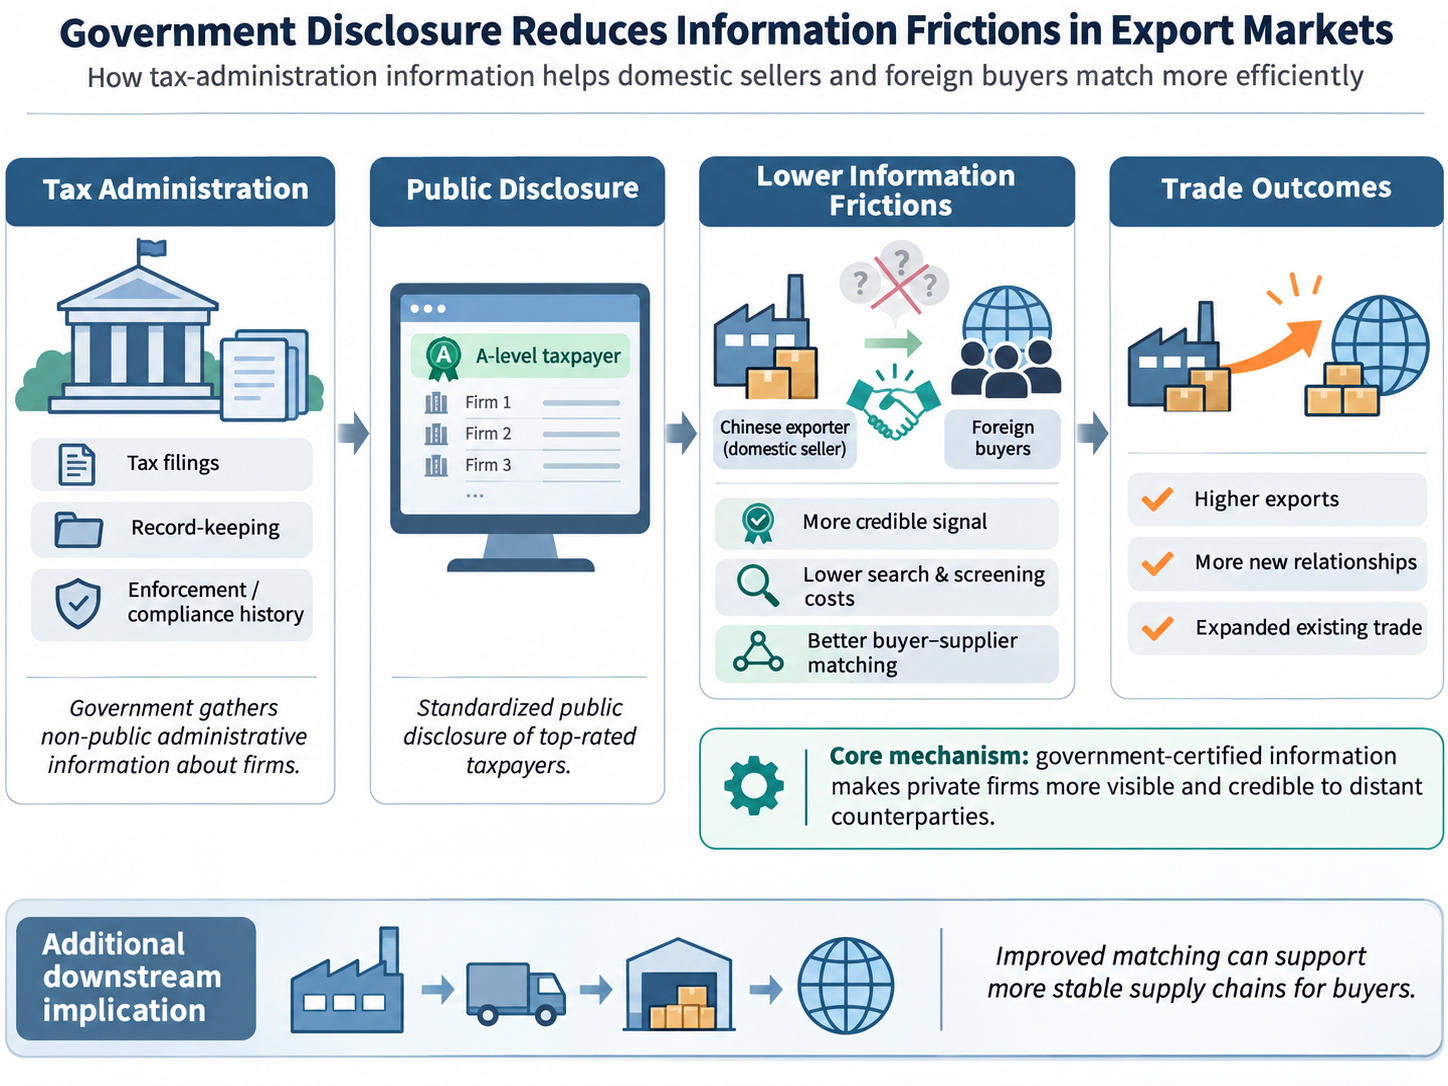
Government disclosure of tax compliance serves purposes beyond enforcement by reducing information frictions in cross-border trade and expanding firm exports.

Abstract

We examine whether governments can act as certification intermediaries for opaque private firms, which rating agencies and auditors rarely cover. We exploit China’s 2015 disclosure of firms receiving the top tax compliance rating, which turned previously fragmented, locally held assessments into a standardized, nationwide public certification. Using transaction-level customs data, we find that certified firms increase exports by 7.4%, mainly by forming new relationships with foreign buyers. Consistent with the rating resolving information frictions, the effects are confined to private firms, concentrated among smaller and younger firms and in regions with lower financial reporting quality, and stronger in destinations where buyers have fewer alternative information channels. We find little evidence of improved credit access, as local banks likely already possess the information the rating conveys. Downstream U.S. importers also experience improved supply chain efficiency. Our results show that governments can certify firm quality by disclosing administrative data, extending certification to firms outside the coverage of private intermediaries.

Presentations

2026 ATA Midyear Meeting, 13th ABFER Annual Conference*, 8th New Institutional Accounting Conference*, China Europe International Business School*, Nanjing University*, Shanghai Jiao Tong University*, Tianjin University of Finance and Economics*

* Presented by a coauthor

Public tax compliance certification increases exports, primarily through new foreign buyers.
Paper overview · open full size

Does Public Tax Compliance Recognition Crowd Out Corporate Philanthropy?

with Travis Chow, Yanju Liu and Le Zhao

Invited to resubmit to Review of Accounting Studies as a new submission

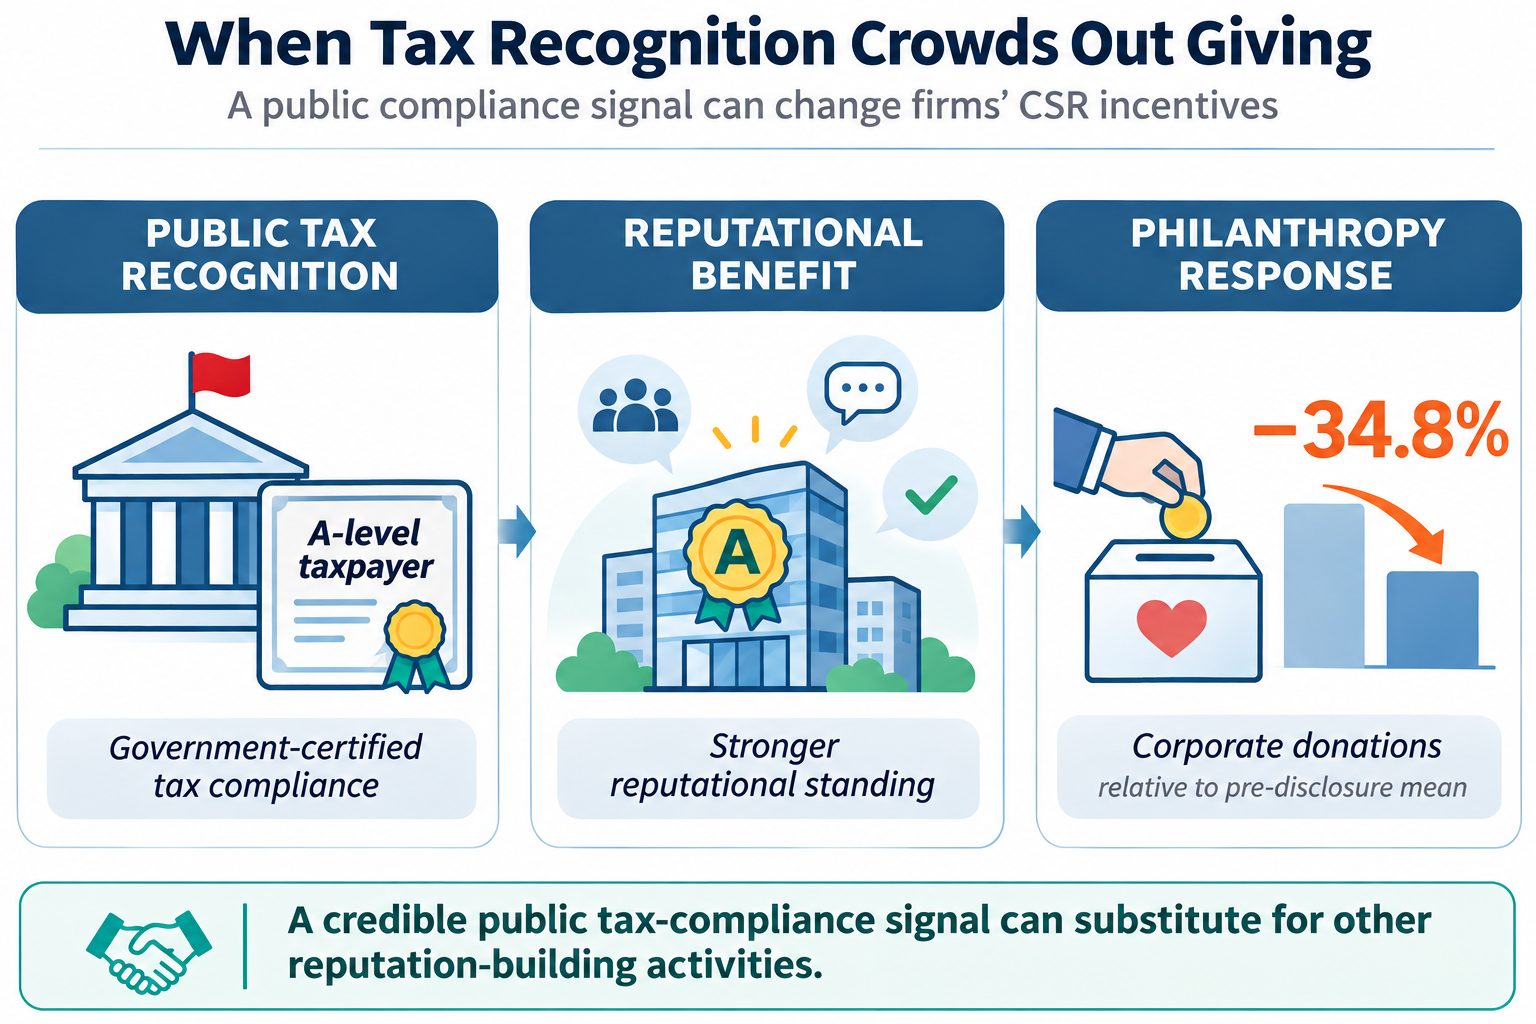
Public recognition of tax compliance crowds out corporate giving by providing firms with an alternative source of reputational capital.

Abstract

Stakeholders have increasingly viewed firms’ tax practices as part of corporate social responsibility. We examine whether public recognition of responsible tax conduct affects firms’ investment in other CSR activities. Using a policy change in China that publicly discloses firms receiving the highest tax compliance rating, we find that corporate donations decline significantly among consistently certified firms. The decline is concentrated along the intensive margin and is larger when the potential reputational value of certification is greater. Additional analyses show that A-level recognition conveys information not readily observable to outsiders, attracts stakeholder attention, and elicits a favorable capital market response. We also find evidence of declines in other dimensions of broader CSR performance. Our findings show that public recognition of responsible tax conduct can reduce firms’ incentives to invest in other reputation-building activities.

Public tax compliance recognition reduces corporate donations among consistently certified firms.
Paper overview · open full size

Discussions